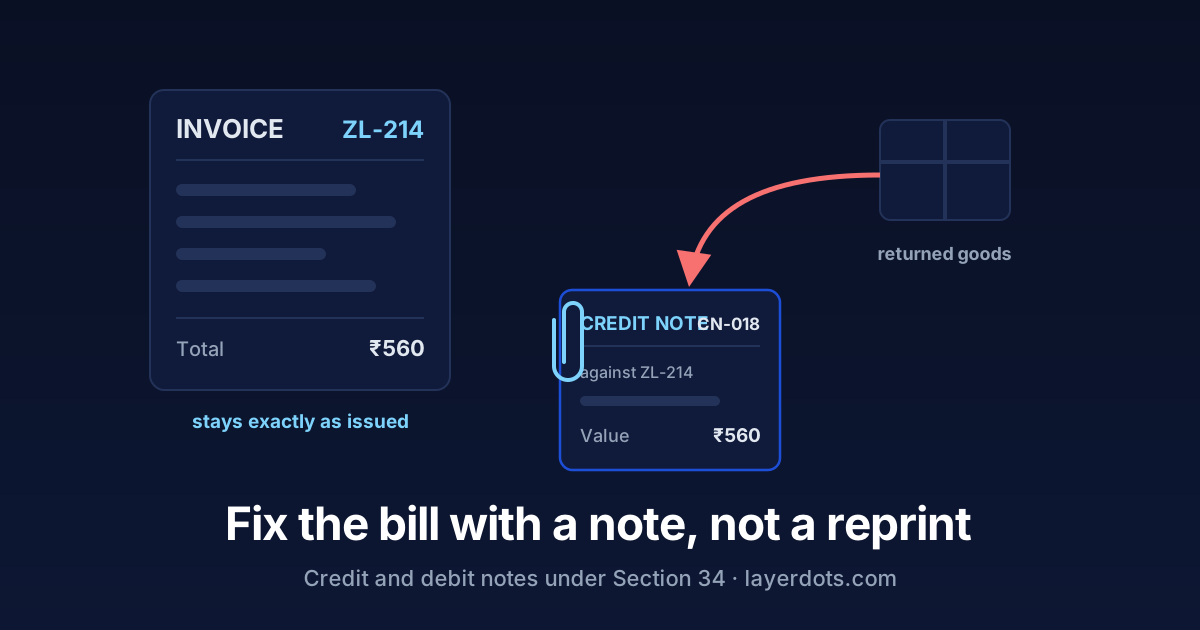
A customer walks back in with last Tuesday's purchase. Or you spot that Tuesday's bill charged ₹1,200 for something that sells at ₹1,020. The tempting fix is to open the old invoice, correct the line and reprint it. Do not. An issued GST invoice is a filed fact, and once it exists the law does not want it edited. It wants a second, smaller document issued against it.
An issued invoice is not edited; Section 34 gives you a second document
Section 34 of the CGST Act is the whole rule. When the taxable value or the tax on an invoice turns out to be more than it should have been, or the goods come back, or the goods or services are found deficient, the supplier issues a credit note against that invoice. When the value or tax turns out to be less than it should have been, the supplier issues a debit note. The original invoice stays exactly as printed: same number, same date, same amounts.
The strictness has a reason. Your invoice has a life beyond your counter. It is in your GSTR-1, and if the buyer is registered it feeds their input tax credit. Rewriting it leaves the government and your buyer holding a version of events that no longer matches yours. The credit or debit note is the trail: anyone can see what was billed, what changed, and why. The same logic covers a bill you want to scrap entirely, which we have covered in what happens to a cancelled invoice number.
Which note: does the customer now owe less, or more
A credit note is for when the customer owes less. Goods returned, an overcharge, a quantity billed but not delivered, a rate typed too high, damaged stock the buyer kept at a discount. You are giving value back. A debit note is for when the customer owes more: you undercharged, missed a line, or applied a lower tax rate than the item carries. A supplementary invoice does the same job, and Section 34(3) treats the two alike.
The names confuse people because accountants use them from both sides of the ledger. Under GST the convention is fixed. Section 34 speaks of notes issued by the supplier. You sold, so you issue. The buyer does not issue a GST credit note back at you.
A counter return, step by step
Say a customer returns one of three items from bill 214, an item worth ₹500 plus ₹60 GST.
- Take the goods back into stock. If you track batches, into the right batch, so the expiry report stays true.
- Issue a credit note referencing invoice 214: the returned item, its value of ₹500, and the ₹60 of tax reversed with it. Rule 53(1A) of the CGST Rules lists what the note must carry, including the serial number and date of the invoice it corrects.
- Refund the ₹560, or set it against the customer's ledger if they buy on credit.
- Leave invoice 214 untouched. It still shows three items, and that is correct: it records what happened on Tuesday, and the credit note records what happened today.
Since 1 February 2019 (the CGST Amendment Act, 2018), one credit note may cover several invoices. For a distributor whose retailer returns a mixed carton against last month's bills that is a real saving in paperwork, and if most of your billing is wholesale billing to registered buyers it comes up every month. Your records should still show which invoices the note settles, because a registered buyer has to match their credit reversal against it.
The 30 November deadline on a credit note
A debit note can be issued whenever the mistake surfaces; it only adds tax, and the government does not object to receiving more. A credit note that reduces your tax has a clock on it. Under Section 34(2) the note must be declared in a return by 30 November following the end of the financial year in which the original supply was made, or the date you file that year's annual return, whichever comes first.
In practice: a sale made any time in 2025-26 can carry a tax-reducing credit note only until 30 November 2026, earlier if you file the annual return before that. Find a 2024-25 overcharge today and the GST part is closed, because that window ended on 30 November 2025. You can still make the customer whole with a commercial credit note that carries no GST adjustment; the money between you is squared, and the tax you collected stays with the government. Do not sit on returns from an old year.
One more condition hides in Section 34(2). Your tax reduction is not allowed if the burden of that tax was passed on and stays passed on. For a B2B note that means your registered buyer must reverse the input tax credit they took on the reversed portion. If they do not, expect the mismatch to surface when the returns are compared.
Where the notes go in GSTR-1
Notes issued to registered buyers are reported document by document in the credit and debit note table of GSTR-1 (Table 9B), each one naming the buyer's GSTIN. Notes against unregistered, walk-in sales do not get a line each; consumer sales enter GSTR-1 as consolidated figures, the return-period figures absorb the reduction, and the unregistered-note table is reserved for the large inter-state consumer invoices that were itemised in the first place.
A cash customer without a GSTIN still gets a credit note. Section 34 does not exempt consumer sales, and your stock and daily totals will not add up without one. The difference is only in reporting: the note does not appear buyer by buyer, but it must still reduce the consolidated consumer figures for the period, and it remains your record of why.
GSTR-3B then carries the net effect in its outward supply figures. A note reported in one return and forgotten in the other is exactly how the two returns come to disagree; if your accountant has ever called about that, our article on GSTR-1 and GSTR-3B mismatches shows how the gap opens and how it is closed.
Number the notes in their own series
A credit note is a document in its own right, and Rule 53(1A) asks the same of it as Rule 46 asks of an invoice: a consecutive serial number, up to sixteen characters, unique for the financial year. Give the notes their own series (CN-001, CN-002, and DN-001 for debit notes) rather than borrowing numbers from the invoice series. A credit note numbered like an invoice leaves a gap-shaped puzzle in the invoice sequence and an awkward conversation at assessment time. The note refers to the invoice it corrects. It never replaces or reuses its number.
This is where software should do the right thing without being asked. In Layerdots ERP the original bill stays as issued in the bill history, the return produces its own document against it, stock goes back into inventory, the customer ledger updates, and the GST reports pick the adjustment up in the right period. The correct path costs no more effort than the wrong one, which is the only way a rule survives a busy counter.